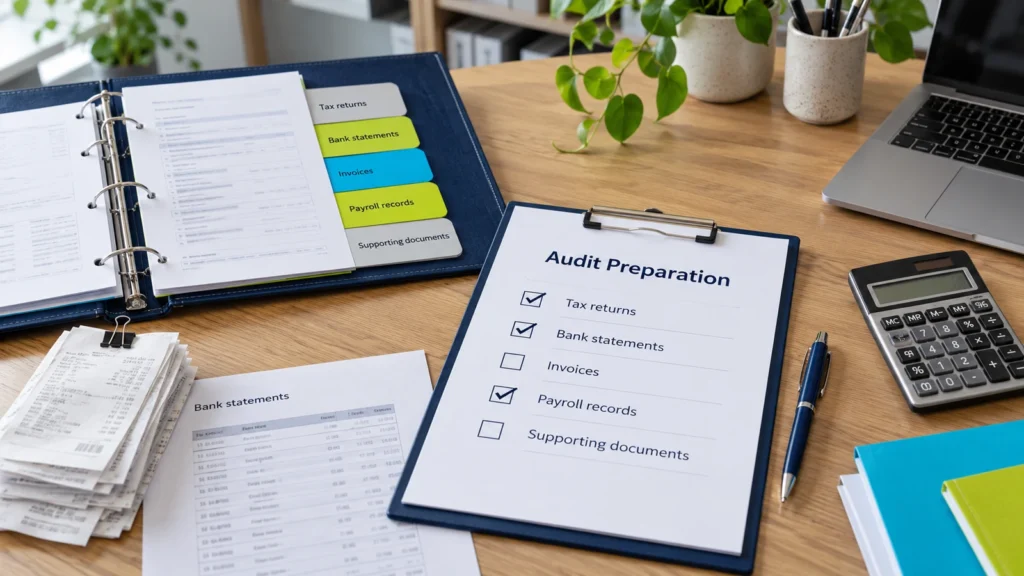
An IRD audit can feel daunting, but the best response is usually a methodical one. If Inland Revenue tells us that a business is being audited or investigated, our first priorities are to understand exactly what is being reviewed, preserve the relevant records, reconcile the information previously filed with IRD, identify any genuine errors and make sure responses to Inland Revenue are accurate, complete and properly supported.
An audit does not automatically mean IRD believes a business has done something wrong. Inland Revenue describes an audit as a check of tax and business records to confirm that the right amount of tax has been paid. An audit can cover areas such as income tax, GST and employer returns. Depending on what the audit finds, a taxpayer could have additional tax to pay or could even be entitled to a refund.
In this guide, we explain the practical steps we recommend New Zealand business owners take when preparing for an IRD audit or investigation.
Important: This guide provides general information only. The correct approach to an IRD audit depends on the business, the tax types involved, the periods being reviewed and the circumstances of any potential error. Professional advice should be obtained for your individual situation.
Quick answer
If your business receives notice of an IRD audit, we recommend that you do not panic, ignore the request or start changing historical records.
Instead:
- Read the IRD communication carefully and identify the tax periods and issues being reviewed.
- Contact your accountant or tax adviser as early as possible.
- Preserve all potentially relevant accounting and source records.
- Gather the documents requested by Inland Revenue.
- Reconcile those records against the tax returns already filed.
- Identify unexplained differences or errors before responding.
- Consider whether any error requires correction or a voluntary disclosure.
- Keep a complete record of information supplied to IRD and correspondence received.
Inland Revenue requires businesses to retain relevant tax records for at least seven tax years. This applies to both paper and electronic records.
The Tax Administration Act also allows the Commissioner to require certain records to be kept for up to a further three years where a taxpayer is, has been, or may be subject to an audit or investigation.
What this means for a New Zealand business
An IRD audit is fundamentally about evidence.
It is not enough for us to believe that a transaction was treated correctly. We need to be able to demonstrate why it was treated that way and, where necessary, connect the amount shown in a tax return back to reliable business records.
For example, if a company claimed $80,000 of business expenses during a financial year, Inland Revenue may want to establish whether those expenses were genuinely incurred by the business, whether they were deductible, whether any private portion should have been excluded and whether the GST treatment was correct.
That means an IRD investigation can extend beyond simply printing a profit and loss statement from Xero.
Depending on what is being reviewed, we may need to work through:
- invoices and receipts
- bank and credit card statements
- GST records
- payroll and employer records
- accounting journals
- general ledgers
- asset purchases and disposals
- depreciation calculations
- loan documentation
- shareholder or director transactions
- expense apportionments
- cash sales
- contracts or agreements
- working papers supporting tax calculations.
Inland Revenue says tax records include information relating to sales, income, expenses, assets and liabilities. Examples include invoices, receipts, bank statements, credit card records, point-of-sale records and cashbooks.
The stronger the audit trail, the easier it generally is for us to explain how a figure moved from the original transaction through the accounting system and into the tax return.
How it works step by step
1. Understand what IRD is asking for
We start with the actual notice or request.
We want to establish:
- which taxpayer or entity is involved
- which tax types are being reviewed
- which financial years or taxable periods are covered
- what records IRD has requested
- whether IRD has identified a particular transaction or concern
- what response dates apply.
We avoid assuming that every part of the business is under investigation if IRD has identified a narrower scope.
2. Preserve the original records
Once an audit or investigation is underway, we make sure relevant information is preserved.
Historical records should not be destroyed or altered to make them look cleaner. Corrections may sometimes be appropriate, but there should be a transparent record of what was changed, why it was changed and when.
Electronic records are particularly important. Inland Revenue says computer-based accounting records must be retrievable and readable and may include transaction-level accounting records, general ledgers, journals, charts of accounts and documentation explaining the accounting system.
3. Reconcile the information before sending it
One of the most valuable things we can do is compare the records with what was actually filed.
For example, we might reconcile:
bank deposits → recorded sales → GST returns → annual accounts → income tax return.
If those figures do not reconcile, we want to understand the reason before the information is sent to Inland Revenue.
A difference does not necessarily mean tax was underpaid. There may be timing differences, transfers between accounts, non-taxable transactions, shareholder funds introduced into the business or other legitimate explanations.
The important point is that we can explain and document them.
4. Identify genuine mistakes
If we find an error, we do not recommend hiding it and hoping IRD does not notice.
We assess what happened, which periods are affected and whether a correction or voluntary disclosure should be considered.
Inland Revenue allows individuals, businesses, trusts and employers to make voluntary disclosures about errors in previous returns.
Timing can be important. As at 3 September 2026, Inland Revenue states that voluntary disclosure can reduce certain shortfall penalties. The potential reduction differs depending on whether disclosure occurs before notification of a pending audit or after notification but before the audit or investigation begins.
This is one reason we recommend seeking professional advice early rather than waiting until an audit has progressed.
5. Respond accurately and systematically
We recommend keeping a clear record of:
- every document requested
- every document supplied
- the date it was supplied
- questions asked by IRD
- explanations provided
- outstanding requests
- deadlines
- discussions with Inland Revenue.
This can become especially important if an audit runs over an extended period or moves between different issues.
Calculations, records or decisions involved
Our tax audit checklist normally starts by establishing whether we can support the numbers already reported.
For a typical New Zealand small business, that may involve reviewing:
Income
We reconcile recorded sales against bank deposits, payment platforms, cash receipts and other sources of revenue.
Expenses
We check that material deductions have invoices or other supporting evidence and that the expense relates to earning business income.
GST
For GST-registered businesses, we check whether GST returned on sales and claimed on purchases matches the underlying transaction records.
Payroll
If the business employs staff, we may need to review payroll reports, PAYE deductions, employment information and payments made to Inland Revenue.
Assets
Purchases of vehicles, machinery, computers and other assets may require us to check whether they were treated as capital expenditure and whether depreciation was calculated appropriately.
Private versus business expenditure
Vehicle costs, home-office expenditure, telephone expenses and other mixed-use costs can require apportionment. We want the calculation and the basis for that calculation to be documented.
In practice, the question we continually ask is: Can we show how this amount was calculated and what records support it?
Common mistakes and risks
The biggest problems we see are often caused by poor documentation rather than complicated tax law.
Common risks include:
- missing invoices or receipts
- unreconciled bank accounts
- cash sales that were not recorded correctly
- personal spending paid through the business
- business expenses paid personally but recorded inconsistently
- incorrect GST treatment
- unsupported expense claims
- inaccurate payroll information
- missing records from older accounting systems
- large journal entries with no explanation
- unexplained loans or shareholder transactions
- inconsistent information between GST returns, financial statements and income tax returns.
Another mistake is delaying or obstructing the investigation.
As at 3 September 2026, Inland Revenue states that a shortfall penalty may be increased by 25% where a taxpayer obstructs Inland Revenue, including by destroying relevant records, providing false information or deliberately delaying enquiries.
For serious deliberate conduct, the consequences can be much greater. Inland Revenue’s current guidance states that the shortfall penalty for tax evasion is 150% of the resulting tax shortfall, with prosecution possible in some cases.
Those rules should not make an ordinary business owner panic. They reinforce why transparency, proper records and early professional advice matter.
Practical checklist
If your business is preparing for an IRD audit, we recommend working through this checklist:
- Read the IRD notice in full.
- Confirm which entity is being reviewed.
- Confirm the tax types and periods covered.
- Note every deadline.
- Tell your accountant or tax adviser.
- Preserve all relevant paper and electronic records.
- Gather bank and credit card statements.
- Gather invoices, receipts and supplier records.
- Export relevant accounting records and ledgers.
- Gather GST records where applicable.
- Gather payroll and employer records where applicable.
- Review asset and depreciation schedules.
- Review loans and shareholder transactions.
- Reconcile filed returns against the underlying accounts.
- Investigate unexplained differences.
- Document assumptions and calculations.
- Identify any errors requiring correction.
- Consider whether a voluntary disclosure is appropriate.
- Keep copies of everything supplied to IRD.
- Keep a log of all communication with Inland Revenue.
Good preparation before an audit is also good everyday business practice. Inland Revenue’s current guidance requires most business tax records to be retained for at least seven years, so record keeping should be treated as an ongoing process rather than something we start when an IRD letter arrives.
Humphries Associates offers Audit Shield Insurance as an option to help protect against the added costs of an IRD audit. For more details, please contact us.
For businesses wanting to strengthen their tax compliance before issues arise, our Tax Return Services page explains how we help manage tax returns and ongoing Inland Revenue obligations.
Related Knowledge Hub guides to link internally:
- Tax Return Checklist for New Zealand Small Businesses
- What Happens If You File or Pay Tax Late in New Zealand?
When to speak with an accountant or business adviser
We recommend getting professional advice as soon as possible when IRD formally notifies you of an audit or investigation, particularly where significant amounts of tax are involved or you already know there may be mistakes in previous returns.
Advice becomes especially important where:
- records are incomplete
- several tax years are involved
- GST, PAYE and income tax issues overlap
- IRD questions significant deductions
- private and business transactions have been mixed
- historical returns appear incorrect
- a voluntary disclosure may be appropriate
- penalties are being considered
- you disagree with Inland Revenue’s proposed tax treatment.
Our role is not to manufacture an explanation after the event. It is to help establish the facts, organise the evidence, identify the correct tax treatment and communicate the position clearly.
If you have received an IRD audit or investigation notice and want help understanding what it means for your business, you can contact Humphries Associates to discuss your situation.
Frequently asked questions
What is the short answer for a New Zealand business?
If IRD tells you that your business is being audited, identify exactly what is being reviewed, preserve your records, speak with your accountant and reconcile the information previously filed before responding. An audit is a review of tax and business records and does not automatically mean IRD has concluded that something is wrong.
What records or information will I need?
The exact information depends on the audit, but it may include bank statements, invoices, receipts, accounting ledgers, GST records, payroll records, asset schedules, contracts and working papers supporting tax calculations. Inland Revenue generally requires business tax records to be kept for at least seven years.
What are the most common mistakes?
Common problems include missing source documents, unsupported deductions, unreconciled accounts, incorrect GST treatment, mixed personal and business expenditure, incomplete payroll records and differences between accounting records and tax returns.
When should I get professional advice?
We recommend seeking professional advice when you receive notification of an IRD audit or investigation, and particularly before responding where you believe previous returns may contain errors. The timing of corrective action or a voluntary disclosure can affect how Inland Revenue treats potential penalties.
General information disclaimer: This article provides general information about New Zealand tax compliance and IRD audits. It is not personalised tax, legal or financial advice. Tax outcomes depend on the facts and circumstances of each taxpayer.